
Physician’s Quick Answer
Ameritas, Guardian, MassMutual, Principal, and The Standard are commonly considered the big 5 disability insurance companies for physicians.
Each offers strong True Own-Occupation coverage for eligible specialties, but differences in cost, underwriting, residual disability benefits, future purchase options, and built-in features can affect which policy ultimately provides you with the best fit and the most value.
In comparing companies, consider which one offers a contract that fits your specialty, health history, income, and career plans without paying more for features than you need.
Choosing disability insurance isn’t about finding the “best” insurance company, it’s about finding the contract that best fits your medical specialty, income, health history, and long-term career goals.
Five of the leading carriers offering True Own-Occupation disability insurance for physicians are Ameritas, Guardian, MassMutual, Principal, and The Standard.
Each offers strong physician-focused protection, but they can differ slightly in future purchase options, residual disability benefits, built-in contract features, underwriting philosophy, and policy flexibility.
Why We Wrote This Guide
One of the most common questions we hear from physicians is:
“Which disability insurance company is the best?”
It’s an understandable question.
After all, when you’re comparing multiple quotes, the policies often appear very similar. The monthly benefits may match. The premiums may be comparable. The own-occupation definition may even look nearly identical.
However, once you begin comparing the details of each contract, there are not many meaningful differences.
The comparison can also depend on who is presenting the options. A captive agent can offer only one carrier, while a carrier-specific representative may focus on that company’s strengths and its competitors’ weaknesses.
Our goal isn’t to recommend one company over another.
Our goal is to help physicians understand what each carrier is commonly known for, and then figure out which company delivers the terms you are looking for at the best possible price.
Before Comparing Carriers
The five carriers featured in this guide all offer True Own Occupation disability insurance for many physician specialties.
That means you’re already comparing some of the strongest disability insurance contracts available.
The differences generally aren’t about whether one company is “good” and another is “bad.”
Instead, the differences often involve:
- Future purchase opportunities
- Residual disability benefits
- Built-in policy enhancements
- Optional riders
- Underwriting philosophy
- Long-term contract flexibility
The right policy depends on your individual circumstances—not simply the company’s name.
What Is a Residual Disability?
A residual disability, also sometimes referred to as a partial disability, occurs when an illness or injury limits your ability to work but does not prevent you from working entirely.
For instance, as a physician with a residual disability, you might work fewer hours, see fewer patients, or stop performing certain procedures and experience a qualifying loss of income. A residual disability benefit can be helpful in replacing part of that lost income.
Depending on the contract, residual disability coverage may be built into the policy or added through a residual disability rider. Carriers can differ in the income loss required to qualify, how benefits are calculated, and whether recovery benefits continue after the physician returns to full-time work.
Permanent partial disability is a term more commonly used in workers’ compensation. Individual disability policies generally rely on their own partial or residual disability definitions, so physicians should review the actual contract language rather than assume any lasting limitation will qualify for benefits.
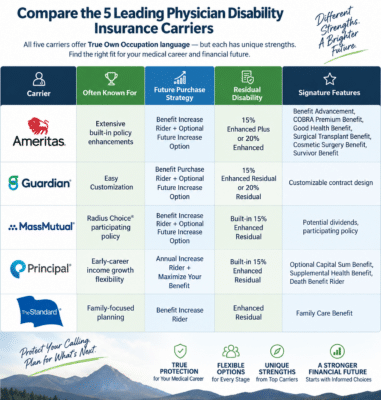
Ameritas
Ameritas is frequently chosen by physicians who appreciate a policy with numerous built-in contract enhancements. In addition to offering True Own Occupation Disability Insurance, Ameritas provides both a flexible Benefit Increase Rider and an optional Future Increase Option (FIO) for physicians whose income is expected to grow over time. You can also include their Automatic Increase Rider (AIR) if you would like to have 4% increases annually for a 5-year period without financial underwriting.
Ameritas also allows physicians to choose between the 15% Enhanced Plus Residual Rider and the 20% Enhanced Residual Rider, providing additional flexibility in how partial disability benefits are structured.
One of Ameritas’ distinguishing characteristics is the number of built-in policy enhancements included within many physician contracts, including benefits related to COBRA premiums, good health incentives, survivor benefits, surgical transplant coverage, cosmetic surgery, and benefit advancement.
Guardian
Guardian’s policy includes a built-in Benefit Purchase Rider, while physicians who expect annual income growth may also elect an optional Future Increase Option (FIO). In addition, they offer their Automatic Benefit Enhancement (ABE) that grows benefits at 3% a year for a 6-year timeline without financial documentation.
Guardian also gives physicians the choice between a 15% Enhanced Residual Rider and a 20% Residual Rider, allowing the residual disability benefit to be tailored to individual planning preferences.
Guardian is also frequently considered by physicians who anticipate practicing or living internationally because its contract generally includes fewer international residency restrictions than some competing policies.
MassMutual
MassMutual’s Radius Choice® policy combines a strong True Own Occupation Disability Insurance contract definition with the unique characteristics of a participating policy that can earn dividends.
Eligible Radius Choice® policies may receive annual dividends beginning after the fifth policy year. While dividends are never guaranteed, MassMutual has paid dividends to eligible participating policyholders for more than 160 consecutive years.
MassMutual also offers a Benefit Increase Rider, an optional Future Increase Option (FIO), and includes a built-in 15% Extended Residual Disability Rider. They also have their Automatic Increase Benefit (AIB) to grow benefits at 3% a year for a 5-year timeline without financial documentation.
Like Guardian, MassMutual is often considered by physicians planning international careers because its policy generally provides fewer international residency restrictions than some competing contracts.
Principal
Principal is well known for helping physicians navigate the early years of practice when income often increases rapidly with True Own Occupation contract definition.
Its physician contracts include an Annual Increase Rider (AI), which automatically increases monthly benefits over time at 3% a year, as well as the Maximize Your Benefit Rider (MYB), which provides additional purchase opportunities based on qualifying income growth and certain life events; especially in the first three years of the contract.
Principal also includes a built-in 15% Enhanced Residual Disability Rider and offers several optional value-added riders, including the Capital Sum Benefit, Supplemental Health Benefit, and Death Benefit Rider.
Many physicians appreciate Principal’s focus on helping disability insurance grow alongside their careers.
The Standard
The Standard combines a strong True Own Occupation Disability contract with thoughtful features that recognize both professional and personal life changes.
Its Benefit Increase Rider (BIR) provides scheduled opportunities to purchase additional disability insurance as income grows every 3-years but also with certain life events. They also have their Automatic Increase Benefit (AIB) to grow benefits at 4% a year for a 5-year timeline without financial documentation.
The carrier is perhaps best known for its distinctive Family Care Benefit, which may provide benefits when an eligible physician experiences a qualifying loss of income while reducing work responsibilities to care for a seriously ill family member.
For physicians balancing demanding careers with family responsibilities, this feature is one of the most unique among the major disability insurance carriers.
The five carriers at a glance
| Carrier | Increase options | Residual benefit | Often chosen for |
|---|---|---|---|
| Ameritas | Benefit Increase Rider; optional Future Increase Option; Automatic Increase Rider (4% a year for 5 years) | choice of 15% Enhanced Plus or 20% Enhanced Residual Rider | many built-in contract enhancements |
| Guardian | built-in Benefit Purchase Rider; optional FIO; Automatic Benefit Enhancement (3% a year for 6 years) | choice of 15% Enhanced Residual or 20% Residual Rider | fewer international residency restrictions |
| MassMutual (Radius Choice) | Benefit Increase Rider; optional FIO; Automatic Increase Benefit (3% a year for 5 years) | built-in 15% Extended Residual Rider | participating policy that may earn dividends (not guaranteed); fewer international residency restrictions |
| Principal | Annual Increase Rider (3% a year); Maximize Your Benefit Rider | built-in 15% Enhanced Residual Rider | early-career income growth |
| The Standard | Benefit Increase Rider (every 3 years and at certain life events); Automatic Increase Benefit (4% a year for 5 years) | not covered in this guide | Family Care Benefit |
Key Comparison Principles
When comparing physician disability insurance contracts, remember:
- Every major carrier offers a strong Own Occupation foundation for eligible physician specialties.
- Premium should never be the only deciding factor.
- Increase Option flexibility becomes increasingly important as physician income grows during the first few years of being an attending.
- Partial disability claims occur more frequently than total disability claims, making residual disability benefits an important part of every comparison regardless of it being a 15 or a 20% loss to trigger benefits.
- Built-in policy enhancements vary significantly among carriers.
- Underwriting philosophies for certain medical history can influence which carrier is the best fit for your medical history or specialty.
- Physicians planning to practice or live internationally should carefully review international coverage provisions before selecting a policy.
Questions Worth Asking
Before choosing a disability insurance carrier, consider asking:
- Which future purchase option best fits my anticipated income growth?
- Which built-in policy features are meaningful to my situation?
- Will international travel or living abroad affect my coverage?
- Which carrier’s underwriting philosophy best aligns with my medical history?
- How does my specialty influence the recommendation?
Key Takeaways
- Ameritas, Guardian, MassMutual, Principal, and The Standard all offer strong True Own Occupation Disability Insurance for physicians.
- The differences are minimal at best when you build them all to look the same.
- Future purchase options, residual disability benefits, built-in enhancements, and underwriting philosophy are often the most important areas to compare.
- There is no universal “best” disability insurance company for every physician.
- The most appropriate policy depends on your specialty, health history, income, career plans, and long-term financial goals.
Learn About Disability Insurance Features
- What Is Own-Occupation Disability Insurance or do you need Own Specialty Definition of Disability?
- Understanding Residual Disability Benefits
- Increase Options Explained
- Understanding Elimination Periods
- Recovery Benefits Explained
- Presumptive Disability Benefits
Ready to Compare Disability Insurance Contracts?
Disability insurance is one of the most important financial decisions physicians make during their careers.
Comparing contracts side by side allows you to evaluate everything, including the premiums—it helps you understand how policy definitions, future purchase opportunities, built-in benefits, and contract flexibility may affect your long-term income protection.
From Scott & Amber’s Desk
After more than 45 years of combined experience helping physicians nationwide, we’ve learned that every major own-occupation disability insurance carrier offers meaningful strengths. The differences are often found in the details—future purchase opportunities, residual disability provisions, built-in contract enhancements, underwriting philosophy, and contract flexibility.
That’s why we don’t begin with the carrier, we begin with the client.
Your specialty, health history, income, career plans, and long-term goals all influence which contract may be the best fit for your situation.
The purpose of this comparison guide isn’t to rank companies. It’s to help physicians understand how the leading disability insurance contracts differ so they can ask better questions and make more informed decisions.
That’s why we created the MD Disability Quotes Knowledge Center—to provide objective, physician-focused education before disability insurance is ever needed.
Every article in the MD Disability Quotes Knowledge Center is written with one purpose: to help physicians understand insurance contracts before they ever need to rely on them.
To take the next step and build a strategy that supports your career and financial future, download the FREE Medical Professionals Blueprint here.
About MD Disability Quotes
MD Disability Quotes is a nationwide disability insurance advisory firm specializing in income protection for physicians, dentists, business owners, and other high-income professionals.
Founded by Scott Nelson-Archer and Amber Stitt, the firm brings more than 45 years of combined experience helping clients evaluate disability insurance contracts, navigate underwriting, and design income protection strategies tailored to specialized careers.
Scott and Amber are the longest-tenured disability insurance experts featured by White Coat Investor. Their education-first approach has helped thousands of physicians better understand disability insurance throughout medical school, residency, fellowship, and practice.
Whether you’re reviewing an existing policy or exploring coverage for the first time, MD Disability Quotes is committed to helping you make informed decisions that protect your ability to earn an income.
If you would like to schedule a disability insurance strategy session, click here.
If you would like to request physician disability insurance quotes, click here.
You can email us: info@mddisabilityquotes.com
Call 713-966-3932 (9 AM-5 PM Central)
Text 281-770-8080 at your convenience.
Written by
Amber has spent over 15 years helping physicians across the country protect their income and make more confident financial decisions. She is one of the longest-tenured advisors serving the physician community through The White Coat Investor.