

Key Takeaways:
- Can you work and still collect disability insurance benefits? Yes, depending on the definition of disability in your policy and whether you qualify for Total or Residual Disability benefits.
- Does True Own Occupation disability insurance allow you to work in another occupation? If you cannot perform the “material and substantial” duties of your specific occupation/own specialty, you will receive full benefits even if you earn income elsewhere.
- Can you receive disability benefits if you reduce your clinical hours? If a disability forces you to reduce your hours, stop performing certain procedures, or earn less, you may qualify for Residual or Partial Disability benefits.
- How are Residual Disability benefits calculated? Depending on the contract, benefits are be based on the percentage of income lost or sometimes hours lost, because of your partial disability.
- Why is the definition of Own Occupation important for physicians? Policy language is critical to determine if you will receive benefits if disabled from your medical specialty, while being gainfully employed to insure no income offsets.
Can You Work and Still Collect Disability Insurance Benefits?
I get some version of this question all the time, in fact it was asked of me this morning.
“If I get disabled, can I still work and collect my disability benefit?” The answer is yes, sometimes, and no, it depends entirely on what your contract actually states.
Can True Own Occupation Disability Insurance Pay Benefits if You Work in Another Role?
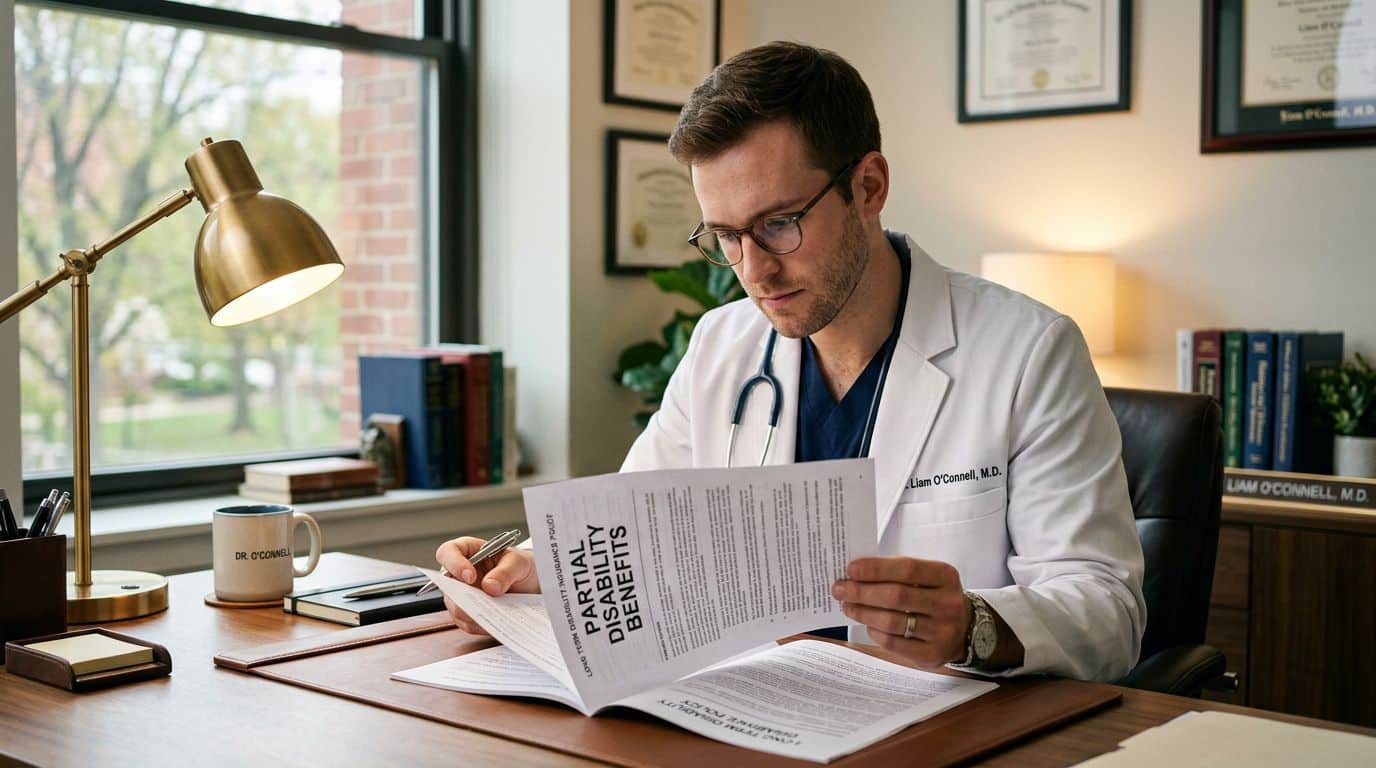
Let’s say you are an anesthesiologist and you develop a back problem. You can no longer handle the long cases, overnight call or the physical demands of practicing the way you do today. But you could still teach, supervise, consult or maybe move into an administrative role.
Can you still collect?
With the right True Own Occupation or Own Specialty definition, yes. If you are unable to perform the duties of your occupation, the contract may still pay a full benefit even if you are earning income doing something else. But here is where people get confused. That does not mean you can simply cut your clinical schedule in half and automatically collect your full disability benefit. If you are still working in your occupation but your disability causes you to reduce your hours, give up certain procedures or simply earn less, then you are probably looking at the Residual or Partial Disability part of the contract.
How Are Residual Disability Benefits Calculated When a Physician’s Income Drops?
For example, assume you are earning $400,000 a year before becoming disabled. After the disability, you can still work, but your income drops to $200,000 because you cannot work the same schedule or perform the same duties. Now you have a 50% income loss. Depending on the contract, that may produce a residual disability benefit tied to that loss of income. Typically the percentage of income lost is the percentage of benefit to be paid when you are working part time in your specialty.
How Do Different Medical Specialties Affect Disability Insurance Claims?
Now take an orthopedic surgeon who can no longer operate but can still see patients in the office. Or an emergency physician who can no longer work in the ER due to physical demands but can still work shorter shifts at an urgent care. Or a radiologist who cannot sit at a workstation all day but can still teach residents.
Those are all different claims.
Why Isn’t an Own Occupation Definition Enough to Understand Your Disability Insurance Coverage?
And this is why I keep telling people that “own occupation” by itself does not tell you enough.
You need to know how the contract defines your occupation, what qualifies as residual disability, how much income loss is required, how the benefit is calculated and what happens if you start earning money in another role. That is the stuff that matters at claim time.
Can Physicians Qualify for Disability Benefits if They Can Still Perform Some of Their Duties?
Most physicians do not go from working full-time one day to being completely unable to do anything the next. A lot of disability claims fall somewhere in the middle. You may still be able to do some of your job. You may be able to work fewer hours. You may be able to teach or supervise. You may be able to earn a good income doing something else.
The question is whether the contract is written in a way that pays the benefit you thought you were buying.
So when someone asks me, “Can I still work and collect disability insurance?” my answer is:
Maybe.
Now let’s read the contract.
From Scott & Amber’s Desk
One of the biggest misconceptions I see among physicians is the assumption that disability insurance only pays when you are completely unable to work.
In reality, many physicians experiencing a disability can still practice medicine in some capacity. They may need to reduce their clinical hours, stop performing certain procedures, or transition into teaching or administrative work.
The important question is not simply whether you can still work. It’s how your disability insurance contract defines your occupation and determines your eligibility for benefits when your ability to earn an income changes.
Before purchasing a policy, I encourage physicians to understand two things: what happens if they can no longer perform the duties of their medical specialty, and what happens if they can still work but experience a reduction in income.
Those are two very different scenarios, and your contract should clearly address both.
Our goal is to help you understand those differences before you ever need to file a claim.
— Scott Nelson-Archer
About MD Disability Quotes
MD Disability Quotes is a nationwide disability insurance advisory firm specializing in income protection for physicians, dentists, business owners, and other high-income professionals.
Founded by Scott Nelson-Archer and Amber Stitt, the firm brings more than 45 years of combined experience helping clients evaluate disability insurance contracts, navigate underwriting, and design income protection strategies tailored to specialized careers.
Scott and Amber are the longest-tenured disability insurance experts featured by White Coat Investor. Their education-first approach has helped thousands of physicians better understand disability insurance throughout medical school, residency, fellowship, and practice.
Whether you’re reviewing an existing policy or exploring coverage for the first time, MD Disability Quotes is committed to helping you make informed decisions that protect your ability to earn an income.
Schedule a disability insurance strategy session.
Request physician disability insurance quotes.
You can email us: info@mddisabilityquotes.com
Call 713-966-3932 (9 AM-5 PM Central)
Text 281-770-8080 at your convenience.